YNAB vs TrackMyStack: Budgeting App vs Net Worth Tracker (2026)
YNAB is a budgeting app. TrackMyStack is a net worth and portfolio tracker. Here is an honest 2026 comparison of pricing, features, and which one solves your actual problem.
Two Apps Walk Into a Spreadsheet…
One says “give every dollar a job before you spend it.” The other says “I don’t really care what you spend, just show me what you own.”
That’s the YNAB vs TrackMyStack situation in one sentence. Both are excellent at what they do. They just don’t do the same thing — and the internet’s habit of cramming them into the same comparison post is mostly the fault of one shared keyword: “personal finance app”.
YNAB is a budgeting app. It’s arguably the best one. TrackMyStack is a net worth and portfolio tracker. It does not budget. If you’ve been wondering which of the two to use, the honest answer is “probably both, for different reasons” — but if you’re going to pick one, you need to know which problem you’re actually solving.
Let’s break it down. (If you came here from the old “YNAB vs Mint” debate, what changed in 2024 is further down.)
YNAB
YNAB stands for “You Need A Budget,” which is the kind of name you can only get away with if your product genuinely delivers. It does. The app is built around a four-rule methodology — give every dollar a job, embrace your true expenses, roll with the punches, age your money — that turns budgeting from “guess and beat yourself up at month-end” into “decide where the money goes before it leaves.”
It’s a forward-looking budgeting tool, not a backward-looking spending report. That distinction is what makes YNAB different from every “budget app” that’s just a categorised receipt collection.
YNAB Features
- Zero-based budgeting: Every dollar in your accounts gets assigned to a category before it can be spent (the method is the product)
- Targets and goals: Funding targets per category, savings goals, debt payoff goals with built-in calculators
- Bank import: Automatic transaction import from banks in the US, Canada, the UK and much of Europe (through Plaid and MX); elsewhere you import files or type transactions in
- Subscription sharing: Share with up to five other people on one subscription — genuinely useful for couples and families
- Reports: Spending, income vs expense, age of money, and a basic net worth report
- Multi-device sync: iOS, Android, web, Apple Watch, with real-time sync across them
- Loan and debt calculators: Project payoff timelines and interest costs
- 34-day free trial: No credit card required if you sign up directly through YNAB
YNAB Pricing
- Annual — $109/year (about $9.08/month equivalent)
- Monthly — $14.99/month
- Free for college students for one year, plus a workplace benefit program
YNAB is one of the most expensive budgeting apps on the market, and it’s also the one most likely to pay for itself in the first month. There’s no way to use it for free long-term — after the 34-day trial, you either subscribe or you stop having a budget.
YNAB: Pros and Cons
Pros:
- The best zero-based budgeting workflow available
- Strong educational ecosystem (workshops, podcast, YouTube, an actual book)
- Genuine community around the method
- Family-friendly subscription sharing for the price of one plan
- Solid net worth report as a bonus
Cons:
- Bank import covers North America, the UK and much of Europe; elsewhere it’s file import or typing
- Investment tracking is balance-only — no holdings, cost basis, or performance metrics
- $109/year is steep if you mostly want net worth or portfolio tracking
- The methodology has a learning curve. If you don’t engage with it, you’re paying $109/year for a fancy spreadsheet.
Who is YNAB for?
YNAB is for people whose financial pain point is “where did all my money go this month.” If you want to plan your spending, build savings habits, get out of debt, and form a real relationship with your money, YNAB is the answer. The price is justified by the behavioural change, not by the feature list.
It is not for people whose pain point is “I don’t know what my net worth is” or “how is my portfolio performing.” Those are different questions, and YNAB will give you a vague answer to both.
YNAB vs Mint in 2026
For years, “YNAB or Mint?” was the standard budgeting question: YNAB’s paid, hands-on method against Mint’s free, automatic account aggregation. That debate ended on March 23, 2024, when Intuit shut Mint down and pointed its users to Credit Karma. Credit Karma has some net worth and cash-flow features, but it’s fundamentally a credit-monitoring and lending-marketplace product, and most Mint users lost features they relied on.
So the 2026 version of the question is different. If you want Mint-style budgeting, YNAB is still one of the strongest options, at a price. If what you mostly used Mint for was the net worth view, that’s the part TrackMyStack does, without linking your bank. We compare seven Mint replacements, free and paid, in Best Mint Alternatives and Replacements.
TrackMyStack
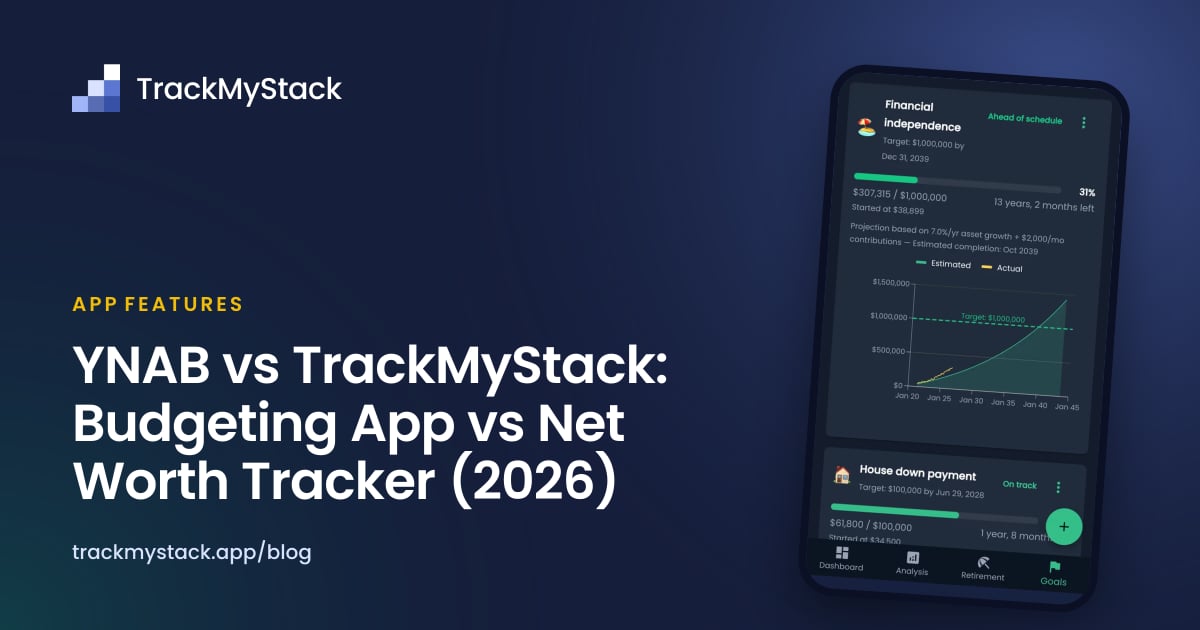
TrackMyStack is a net worth and portfolio tracker that works without linking any financial accounts. You add your assets — stocks, ETFs, crypto, real estate, cash, loans, gold, whatever — and the app updates prices for supported holdings automatically. Your data syncs securely between your phone and the web, and your account is anonymous: no name or email needed.
There’s no sign-up form and no bank login. Open the app, start adding holdings, and you’re tracking your net worth within a few minutes. It’s designed for people whose first thought when an app asks for their email is “why.”
For the YNAB-vs-TrackMyStack debate specifically, TrackMyStack is the answer to the question YNAB can’t really answer: what do I own, what is it worth right now, and how is it performing?
TrackMyStack Features
- Unlimited portfolios and assets on the free tier — not a 3-account demo
- Automatic price tracking for supported stocks, ETFs, and crypto (end-of-day on Free, real-time intraday on Premium)
- Multi-currency portfolios — each portfolio can be in its own currency, with your total in your home currency. Crypto holdings count too, if you enjoy assets that move 8% before lunch
- Historical dividend tracking on Free; upcoming dividends on Premium
- Cost basis and unrealised P/L — see what you paid versus what it’s worth
- Allocation analysis — by portfolio, asset and currency on Free; by asset type, sector and region on Premium; with a hide-amounts mode for shoulder-surfing protection
- Portfolio Vitals (Premium) — alpha, beta, Sharpe ratio, standard deviation
- Performance over multiple time frames — 1W / 1M / 6M / YTD / 1Y / MAX
- Include / exclude portfolios from net worth — useful for watchlists, kids’ accounts, or speculative buckets
- Portfolio ownership % for shared assets
- Portfolio tags for grouping by tax bucket, liquidity, or goal
- App lock with Face ID or fingerprint in the iPhone and Android apps
- Cross-device sync via QR code, recovery email, or sync key
- Full data export — JSON or Excel, your data, your rules
- Retirement Planner — free Monte Carlo FIRE planning; Premium adds a custom market preset plus legacy and life events
- iPhone, Android, and web apps
TrackMyStack Pricing
- Free — Unlimited portfolios and assets, end-of-day prices, historical dividends, import/export, biometric protection, syncing
- Premium — Optional subscription; price varies by app store and country. Adds real-time intraday prices, upcoming dividends, full Portfolio Performance and Vitals, advanced Retirement Planner options, and priority support. 1-week trial.
The free tier is fully functional. You can run TrackMyStack for years on Free and never hit a fake paywall.
TrackMyStack: Pros and Cons
Pros:
- Free tier that’s actually free, not a marketing trick
- No sign-up and no banking credentials shared with anyone
- Real investment tracking — holdings, cost basis, dividends and allocation on Free, deeper performance analysis on Premium
- Multi-currency portfolios with totals in your home currency
- iPhone, Android, and web apps
- Works in any country
- Premium costs a fraction of YNAB’s $109/year at US prices
- Full data export at any time, no lock-in
Cons:
- No budgeting or expense-tracking features (this is intentional)
- No bank or brokerage account aggregation — you add holdings yourself, prices update automatically
- No advisor sharing or multi-user portfolios
Who is TrackMyStack for?
TrackMyStack is for individual investors who want a complete picture of their net worth and portfolio performance, without handing their banking credentials to a third-party aggregator. It’s a particularly strong fit if:
- You want to see your full financial picture but don’t need (or want) help with day-to-day spending
- You’re outside the US or Canada and tired of apps that pretend the rest of the world doesn’t exist
- You hold assets in multiple currencies, including crypto
- You don’t want to create yet another account just to look at your own numbers
- Your real question is “how am I doing?”, not “where did this month go?”
TrackMyStack is the best choice for investors who want a private, no-signup net worth and portfolio tracker — without paying for budgeting features they’re not going to use.
YNAB vs TrackMyStack: Head-to-Head
| YNAB | TrackMyStack | |
|---|---|---|
| Primary approach | Zero-based budgeting | Net worth & portfolio tracking, manual entry with auto prices |
| Price | $109/year or $14.99/mo | Free (optional Premium) |
| Free tier | No (34-day trial) | Yes, fully usable |
| Trial | 34 days | 1 week (Premium) |
| Account linking | Yes (US, Canada, UK and much of Europe) | No — privacy by design |
| Asset coverage | Bank balances, basic investment balances | Stocks, ETFs, crypto, cash, real estate, loans, more |
| Investment tracking | Balances only | Holdings, cost basis, dividends, allocation; performance analysis on Premium |
| Multi-currency | Single currency per budget | Yes (per-portfolio) |
| Platforms | iOS, Android, Web, Apple Watch | iOS, Android, Web |
| Offline access | Limited | Read-only (last synced data) |
| Privacy model | Bank linking through Plaid or MX | No accounts linked; data syncs securely between phone and web |
| Sign-up required | Yes | No (an anonymous account is created for you) |
| Works outside US/Canada | Budgeting yes; bank import in the UK and much of Europe only | Yes, fully |
| Family sharing | Yes (up to 6 people) | No |
| Budgeting | Yes — its entire purpose | No |
| Net worth tracking | Basic report | Core feature |
Is TrackMyStack a Good YNAB Alternative?
Honestly? Only if you don’t need a budgeting app. If your goal is to plan and control your monthly spending, TrackMyStack will not help — that’s not what it’s built for, and it would be a bad alternative for anyone whose actual problem is budgeting.
If your goal is to see your wealth grow over time, track investment performance, and maintain a private record of everything you own without sharing bank credentials, then TrackMyStack solves a problem YNAB doesn’t really attempt.
A lot of people use both: YNAB for the monthly budget, TrackMyStack for the long-term net worth and portfolio view. Each tool actually does its job well.
The Bottom Line
YNAB and TrackMyStack are not really alternatives. They’re complements that happen to share a search-results page.
If your problem is “I don’t know where my money goes each month and I want to fix that” — YNAB. The $109/year is the price of a method that works. Don’t pick TrackMyStack for this; we don’t budget.
If your problem is “I want to see my complete net worth, track my investments, and check on my portfolio without giving up my bank credentials” — TrackMyStack. Free for unlimited portfolios and assets, retirement planning included, with optional Premium if you want real-time prices and deeper analysis.
Simple test: do you need to plan your spending, or do you need to see your wealth?
- Plan → YNAB.
- See → TrackMyStack.
- Both → both: YNAB for the monthly budget, TrackMyStack for the long-term picture.
Frequently Asked Questions
Is TrackMyStack a good YNAB alternative? Only if you don’t need a budgeting app. TrackMyStack is a net worth and portfolio tracker — it doesn’t replace YNAB’s budgeting. Many people use both: YNAB for monthly budgeting, TrackMyStack for net worth and investment tracking.
Does YNAB track investments and net worth? YNAB tracks account balances and shows a basic net worth figure. It does not track individual holdings, cost basis, performance, or dividends. For real investment tracking you need a portfolio tracker like TrackMyStack.
Is YNAB worth $109 a year? If you actually use the YNAB method, it can pay for itself quickly: YNAB says the average user saves $600 in their first month. If you only want net worth or portfolio tracking, $109/year is hard to justify — TrackMyStack covers that for free.
Can TrackMyStack replace YNAB for budgeting? No. TrackMyStack does not have budgeting, expense categorisation, or bill tracking features. That’s a deliberate scope choice, not a planned addition.
Which app is better for non-US users? TrackMyStack works fully internationally with multi-currency support and no dependence on bank-link integrations. YNAB works internationally for budgeting, and its bank import covers the US, Canada, the UK and much of Europe; elsewhere you import files or enter transactions manually.
Does TrackMyStack require an account? You don’t sign up: an anonymous account is created for you, with no name or email required, and you never share banking credentials. Your data syncs automatically and securely between your phone and the web; you can sign in on another device with a QR code, your sync key, or an optional recovery email.
What about the cost difference? YNAB is $109/year. TrackMyStack Premium costs a fraction of that in the US, and the free tier is fully usable indefinitely. They’re solving different problems, so the comparison is mostly apples to oranges — but if you only need one of them, TrackMyStack is dramatically cheaper.
Is Mint still available in 2026? No. Intuit shut Mint down on March 23, 2024 and moved users to Credit Karma, which is a credit-monitoring product rather than a true replacement for Mint’s budgeting and net worth features. Our Mint alternatives guide compares what people switched to.
Does TrackMyStack connect to my bank like Mint did? No, and that’s deliberate. You add your holdings yourself, and the app updates prices for supported assets automatically. No banking credentials are shared with TrackMyStack or any third-party aggregator.