Should Your House, Pension and Car Count in Your Net Worth?
Should your house, pension and car count in your net worth? Why people disagree, how to value each one honestly, and how to track total and liquid net worth.
The Short Answer
Net worth is everything you own minus everything you owe. By that definition your house, your pension and your car all count, and so do the mortgage, the car loan and the student loan.
The long-running argument on r/Fire, r/FIREUK and every other money forum is about which question the number should answer. “How wealthy am I?” and “How close am I to not needing a job?” need different numbers.
So most people who track this seriously keep two:
- Total net worth: everything at a realistic value, minus all debts.
- Investable net worth: only what is invested or could be spent, leaving out your home, your car and your stuff.
Pick your rules, write them down and apply them the same way every month.
Why People Disagree
There are three common views, each answering a different question:
- Total net worth answers “what’s on my balance sheet?” Everything counts.
- FI net worth answers “how close am I to financial independence?” It leaves out the home you live in: you have to live somewhere, and rules of thumb like the 4% rule are about drawing income from investments. You can’t sell a bedroom a year. Pensions usually stay in, since retirement will run on them.
- Liquid net worth answers “what could I get my hands on soon?” Cash plus investments you can sell without penalty. Locked pensions and a house that takes months to sell are out.
None of these is wrong. The mistakes are comparing your total with someone else’s investable number, and quietly changing the rules so the chart jumps for no real reason.
Your House: Count the Equity, Value It Honestly
What counts is home equity: the market value minus the mortgage. Counting the house without the mortgage is the fastest way to feel rich, and it has no other benefits.
Include it in total net worth. For an FI number, most people leave out their main home. The exception is a rental property: it earns income, so it belongs in your investable view, with its mortgage.
How to estimate the value honestly:
- Use sold prices, not asking prices. Recent sales of similar homes nearby are the best evidence. In England and Wales, HM Land Registry lets you look up what homes sold for.
- Treat online estimates as a range. Zillow’s own figures put the median error of its Zestimate at around 2% for homes on the market and around 7% for homes that aren’t, and half of homes are further off than that.
- Or index it. Take what you paid, or a recent valuation, and move it with an official index: the UK House Price Index, published monthly by HM Land Registry, or the FHFA House Price Index in the US, which goes down to ZIP code level. Boring, but hard to fool yourself with.
- Round down, not up. When three estimates disagree, the highest one is rarely the honest one.
Selling costs are the other haircut. In the UK, the HomeOwners Alliance puts the average high-street estate agent fee at about 1.4% including VAT, before legal fees. In the US, Opendoor says listing agents typically charge 2.5–3%, plus 1–3% in closing costs. Some people deduct a flat percentage to show what they would actually walk away with.
How often to update: the mortgage falls every month, so update it monthly or quarterly. The house value only needs updating once or twice a year. Refreshing it weekly from an online estimate mostly adds noise.
Defined-Contribution Pensions, 401(k)s, ISAs and SIPPs
A workplace DC pension, SIPP, 401(k), IRA or ISA has a balance made of investments with market prices. Count it at its current value.
Pensions drop out of liquid net worth: UK pensions normally can’t be accessed before 55, rising to 57 from April 2028, and US 401(k) withdrawals before 59½ usually carry a 10% additional tax. More on bridging that gap in Workplace Pensions for Early Retirement.
The real question is tax. £100,000 in a SIPP and £100,000 in an ISA are not the same amount of money:
- ISAs (Lifetime ISAs aside) can be withdrawn at any time without losing their tax benefits.
- UK pensions usually let you take up to 25% tax-free, capped by your lump-sum allowance (normally £268,275 across all your pensions); the rest is taxed as income.
- US traditional 401(k)s and IRAs are taxed as income on withdrawal. Qualified Roth withdrawals are not.
Most people count the face value and remember that pre-tax pots are worth less than they look. Others apply a rough haircut to pre-tax accounts based on the tax rate they expect in retirement: more realistic, but a guess about future tax rules. Either way, apply it to every pre-tax account, every time.
Defined-Benefit Pensions: The Hard One
A defined-benefit (final salary or career average) pension is a promise of income, not a pot of money. There’s no balance to look up. The UK State Pension and US Social Security raise the same question. There are three common approaches:
1. Leave it out and treat it as income. Popular in FIRE circles. The pension reduces how much your portfolio needs to cover, so it shows up in your target, not your net worth. But your net worth will understate your position, sometimes by a lot.
2. Use the transfer value. UK schemes will quote a cash equivalent transfer value: what they’d pay to move your pension elsewhere. It’s a real number, but it moves with interest rates, and a second quote within 12 months may cost you. The XPS Transfer Value Index, which follows a 64-year-old with a £10,000-a-year inflation-linked pension, stood at £270,000 at the end of November 2021 and around £137,000 in October 2025. The promise didn’t change; the number roughly halved. Transferring a DB pension worth more than £30,000 legally requires regulated advice, so this is a valuation, not cash you can easily reach.
3. Use a rough capitalised value. Multiply the annual pension by a fixed factor, say 20, and adjust down if it starts much later or isn’t inflation-linked. It’s a convention, not a market price, but it’s stable and easy to explain to your future self.
A common compromise is to leave it out of your FI number and include it in total net worth using option 2 or 3. Whichever you pick, keep it separate, so you can see your net worth with and without it.
Cars and Other Things That Lose Value
A car is an asset with a resale value. A car loan is definitely a liability. Whatever you decide about the car, always count the loan.
The case for leaving it out is depreciation. Kelley Blue Book says most new cars lose about 20% of their value in the first year and around 55–60% within five years. A car is closer to spending than investing: you’ll replace it, and it won’t fund your retirement.
The case for including it: it’s real money you could raise in a week, and counting the loan without the car makes your net worth drop the day you drive it home.
If you include it, use a realistic private-sale or trade-in value, not what you paid, and update it once or twice a year. Furniture, electronics and clothes: almost everyone leaves them out. Tracking your sofa is a commitment few people want.
The Edge Cases
- HSAs (US). Contributions are deductible, withdrawals for qualified medical costs are tax-free, and after 65 other withdrawals are taxed as income without the additional tax. Most people treat an HSA like a retirement account.
- Unvested RSUs and stock options. Unvested RSUs aren’t yours yet: they’re usually forfeited if you leave, and taxed as income when they vest. Most people count only vested shares, and vested options at roughly share price minus strike price, after tax.
- Collectibles. Art, watches, wine, cards: count them only if you would actually sell, at what a dealer would pay you, not the insurance valuation.
- Money owed to you. Count it if you expect to be repaid. The loan to your brother that nobody mentions at Christmas probably doesn’t qualify.
- Student loans. It’s a debt, so count it. In the UK, Plan 2 loans are written off 30 years after the April you were first due to repay, and Plan 5 loans after 40. If you don’t expect to repay in full, showing the balance separately is reasonable, as long as you’re clear about it.
A Practical Setup: Two Numbers, One Set of Rules
- Track total net worth: everything you own at realistic values minus everything you owe, including home equity and pensions.
- Also track an investable view: investments, cash and DC pensions, without your home, cars and possessions.
- Write your rules down. “House: index-adjusted each January, minus 3% selling costs. DB pension: 20 times the annual pension. Car: excluded, loan included.” One paragraph saves a lot of arguing with yourself later.
- Update on different clocks. Cash, investments and loans monthly; property and cars once or twice a year.
Consistency beats precision: the trend matters more than the exact value of your house. For more on methods, see Different Ways to Track Your Net Worth.
How to Track It in TrackMyStack
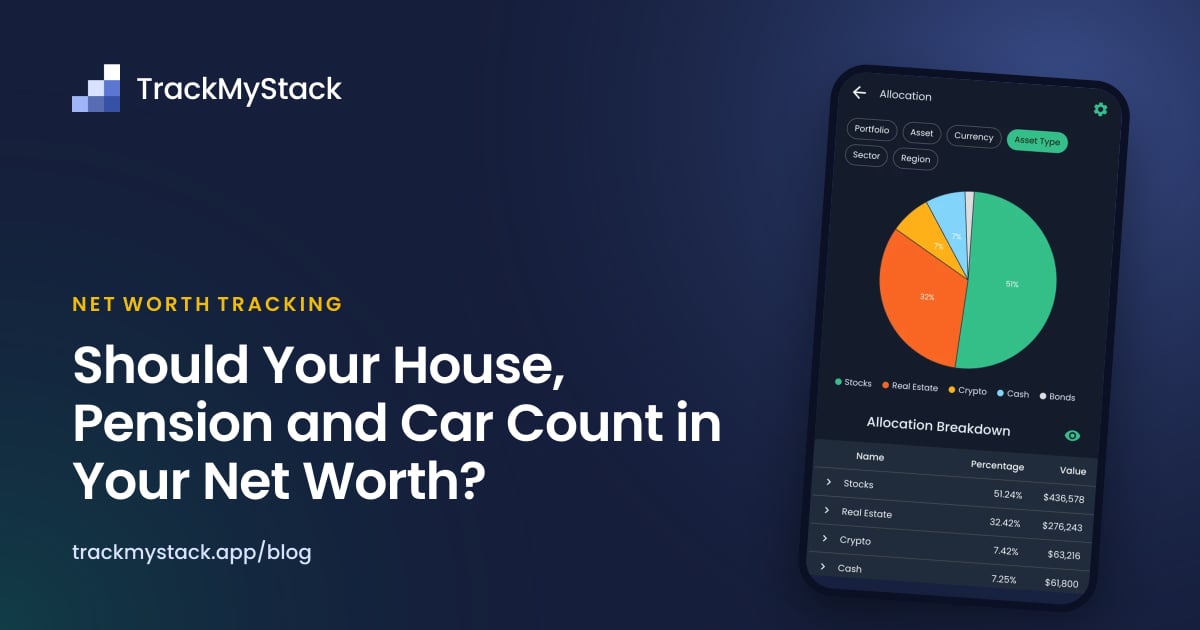
TrackMyStack is a net worth tracker that doesn’t link to banks or brokers. Houses, DB pensions and cars aren’t in a bank feed anyway, so manual holdings do the work here.
- House and mortgage as one holding. Add your home as a manual “Asset with Liability”: enter the value and the mortgage, and the app shows the net value.
- Dated values. Each update is saved with its date, so last year’s numbers stay as they were.
- Monthly reminders. The “Update manual holdings” page lets you update all manual values in one go, with an optional monthly reminder on a day you choose.
- Ownership percentage. Own the house with a partner? Put it in its own portfolio and set ownership to 50%. The same setting can account for tax, for example 80% on a pre-tax pension portfolio.
- Tags. Group portfolios as Real estate, Retirement accounts or Depreciating assets so the split stays readable.
- “Include in net worth” switch. Keep the house, car or DB pension in their own portfolios and switch them off to see your investable net worth. They stay tracked, with full history.
- Goals. A Retirement goal can be linked to specific portfolios, so progress counts your investments and pensions, not your kitchen. Free accounts get one goal; more need Premium.
Stocks, ETFs and funds from the market catalog update their prices automatically. It’s free, with an optional Premium subscription.
Frequently Asked Questions
Should I include my house in my net worth? Yes in total net worth, at market value minus the mortgage. Many people leave their main home out of their investable or FI net worth, because they need somewhere to live and it doesn’t produce income.
Does my pension count towards my net worth? Yes. DC pensions, 401(k)s and SIPPs count at their current value, though pre-tax accounts are taxed when you draw them. A DB pension has no balance, so you either treat it as income or estimate a value.
Should I count my car in my net worth? It’s optional. If you include it, use a realistic resale value and update it occasionally. Either way, count any car loan.
What’s the difference between net worth and liquid net worth? Liquid net worth only counts what you could turn into cash quickly without penalties, so it usually leaves out property and pensions you can’t access yet.
The Bottom Line
By the strict definition, your house, pension and car all count. The useful question is which number you’re looking at. Track a total that includes everything and an investable figure that leaves out the roof over your head and the car on the drive. Value illiquid things conservatively and never change the rules without writing it down. A boring, consistent number tells you far more than a flattering one.