The Best Net Worth Tracker for UK, European, and International Investors (2026)
The best net worth trackers for investors outside the US in 2026: real multi-currency, local exchanges, no US-only bank links. UK, Europe, India, Japan, NZ and more.
When Your Home Currency Is Not the Default
Open almost any popular net worth tracker built in California and you will find a quiet assumption baked into the entire product: your home currency is US dollars. Your bank is a US bank. Your brokerage is a US brokerage. Your “international diversification” is buying VXUS in your Schwab account. Anything else is treated as an exotic FX situation with a converted-to-USD asterisk next to it.
If you actually live in London, Madrid, Zurich, Dubai, Nairobi, Mumbai, Kuala Lumpur, Tokyo, Auckland, or anywhere else where the currency on your payslip is not USD, this gets old quickly. You do not want your house in Hampstead displayed as “$1,420,103.42 (1.27 GBP/USD).” You want it in pounds, you want your ISA in pounds, you want your euro side-pot in euros, and you want one number at the top that adds up correctly with today’s actual exchange rates.
This guide covers the legitimate options for tracking net worth and portfolios as a UK, European, or otherwise non-US investor in 2026 — what each one does well, what it costs, and who it is actually for. We will be specific about which tools politely refuse to work outside their home country, which ones put a dollar sign on every currency, and which ones treat multi-currency as a real feature instead of a setting in a dropdown.
Why Most US-First Apps Fall Short Here
Before the recommendations, the elephants in the room. Three of the most-Googled net worth apps — Empower (formerly Personal Capital), Monarch Money, and Mint — are effectively closed to you. Mint is simply gone: Intuit shut it down in 2024 and moved its users to Credit Karma. Empower needs a US phone number to sign up and only links US financial institutions; anything else has to be typed in as a manual account. Monarch is available in the US and Canada only, and it doesn’t convert currencies at all — in its own words, a 10,000 CAD account and a 10,000 USD account show up as “$20,000.” Empower also has an advisor sales motion attached. They are excellent products if you live in Cleveland. They are not on this list because they cannot serve you if you don’t. (If you want the background on how that account linking works, see what a bank aggregator is.)
Kubera is the high-end exception — it works internationally, supports many currencies, and runs several aggregators, local and global, to connect to thousands of banks and brokerages worldwide. As of October 2026 it also costs $250 to $2,500 per year (Essentials to Black, with a $10,000 “Gold” tier above that), which is fine if your balance sheet has the word “trust” on it and absurd if it doesn’t. We covered the trade-offs in Kubera vs TrackMyStack.
The rest of this guide is the actual non-US shortlist.
Quick Comparison
| App | Home market | Price (as of October 2026) | Free tier | Multi-currency | Account linking |
|---|---|---|---|---|---|
| TrackMyStack | Global | Free, optional Premium | Yes | Per-portfolio currency, totals in your home currency | None — manual entry, file import, or an AI assistant |
| Sharesight | NZ / AU / UK / global | Free (10 holdings) to £21/mo (UK, billed annually) | Yes, capped at 10 holdings, 1 portfolio | Yes; the multi-currency valuation report needs Standard or Premium | Broker trade-confirmation emails, file uploads, some direct broker connections |
| Parqet | Germany / DACH | Free / Plus €11.99/mo | Yes (1 portfolio, 5 non-security assets) | Yes, 40+ currencies | Autosync with German brokers (Trade Republic, Scalable Capital, etc.) |
| Portfolio Performance | Germany / EU | Free, open source | Whole desktop app is free | Yes, ECB exchange rates built in | None — desktop import / manual |
| Ghostfolio | Switzerland / EU | Free Basic cloud / $48 yr Premium / free self-host | Yes (Basic cloud or self-hosted) | Yes | None — manual / file import |
| getquin | Germany / EU | Free / €89.99 yr Premium | Yes | Not confirmed | Bank and broker connections |
A note on what isn’t here: Stock Events, Snowball Analytics, and Delta all work internationally to varying degrees, but they are investment-focused trackers. Stock Events and Snowball do let you add custom assets such as a house or a savings account, but their tools are built around stocks, funds and dividends rather than a whole balance sheet with loans and mortgages. If you mainly want an investment tracker, those are reasonable picks.
1. TrackMyStack — Best Overall for Anyone Whose Currency Isn’t USD
TrackMyStack is a private net worth and portfolio tracker that works without linking any bank, brokerage, or crypto exchange account. You enter what you hold — your ISA, your SIPP, your German Depot, your euro savings account, your Bitcoin, your flat in Lisbon, your mortgage — or import a statement file, and prices for supported holdings update automatically. End-of-day pricing is free; live prices (where available) are on Premium. There is no signup wall, no email required, no Google login, and no “we’re sorry, this product is not available in your region” page. Your data syncs securely, so the phone apps and the web app show the same numbers.
Why it works particularly well outside the US:
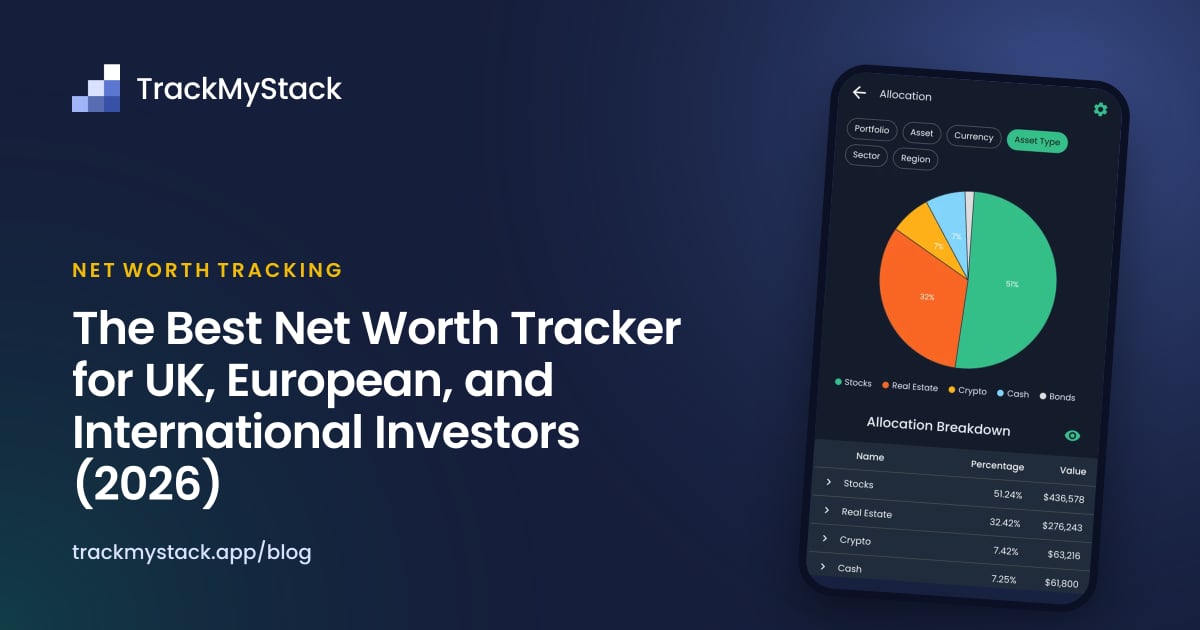
- Real multi-currency portfolios. Each portfolio has its own currency. Your UK ISA sits in GBP. Your Eurozone broker account sits in EUR. Your US brokerage account sits in USD. The net worth figure at the top adds everything up in your home currency at current rates, and the allocation view breaks your money down by currency, so you can see how much of it is really riding on the dollar.
- Pick your home currency, not the app’s. GBP, EUR, CHF, AUD, NZD, SGD, JPY, INR, MYR, KES, AED, SAR — set it once in Settings, and that is the unit your net worth is reported in. Changes are calculated correctly: a flat dollar day with a strong pound day is not a “you got richer” day for a London-based investor, and the app reflects that.
- No bank-link dependency. This matters more outside the US than inside, because the moment you ask a Plaid-style aggregator for “my Belfius account in Belgium” or “my Revolut Stocks balance,” you discover that aggregator coverage is patchy and expensive. Manual entry sidesteps the entire category — and incidentally also sidesteps the periodic consent reconfirmation for UK open banking and the periodic bank reauthentication (every 180 days) in the EU.
- Stock and ETF coverage across exchanges. London, Xetra, Euronext, Milan, Madrid, SIX, the ASX, NZX, India’s NSE and BSE, Tokyo, Bursa Malaysia, the Saudi Exchange — listed shares and ETFs update prices automatically. If a niche local fund isn’t covered, you add it as a manual holding and record a new dated value whenever it changes (there is a page for updating all of them at once, with an optional monthly reminder).
- Shared and partial ownership. A portfolio can count at a percentage of its value, so the flat you own half of with your sibling back home counts at 50%. A house can also sit with its mortgage as a single “asset with liability,” showing the net value.
- iPhone, Android, and web. Plus home-screen widgets, so you can glance at the total without opening the app.
The free tier covers several portfolios with no cap on holdings, end-of-day prices for stocks, ETFs, funds, crypto, and precious metals, the full net worth history chart, allocation by portfolio, asset, and currency, paid-dividend history, the retirement planner, a PIN / Face ID / fingerprint lock, file import, and export to JSON or Excel. Premium is an optional subscription with a one-week free trial; it adds live prices where available, upcoming dividends, allocation by asset type, sector, and region, full performance details, and more than one goal. Its price is set per app store and country, so check it in the app.
What it does not do:
- It does not connect to your UK bank or EU broker. If you want every dividend and trade auto-imported, see Sharesight, Parqet, or getquin below. Manual entry is a deliberate trade-off, not an oversight.
- It does not file tax forms. UK CGT, German Abgeltungsteuer, Australian CGT — for those you want a specialist tool or an accountant.
TrackMyStack is the best choice for UK, European, and international investors who want a private, no-signup net worth tracker with proper multi-currency portfolios, their own currency as a real home currency, and no dependency on US-centric bank aggregators.
2. Sharesight — The Dividend and Tax-Report Heavyweight From New Zealand
Sharesight is the closest thing the non-US world has to a category leader in investment tracking. It was founded in New Zealand, has offices in Wellington and Sydney, has serious UK and Australian followings, supports a long list of global stock exchanges, and is genuinely good at the thing it focuses on: dividend tracking, corporate actions, and tax reporting (which reports you get depends on your tax country).
Pricing as of October 2026 (UK plans, GBP, per month billed annually): Free at 1 portfolio and 10 holdings (closed positions count), Starter £6/mo at 30 holdings, Standard £14/mo for unlimited holdings and four portfolios, Premium £21/mo for ten portfolios. Paying monthly costs more. The free plan has no tax reports; the multi-currency valuation report is on Standard and Premium.
Where it shines: dividend tracking with corporate-action handling, a taxable income report that totals your dividends and interest, and trade imports from broker confirmation emails, spreadsheets, or a direct connection for some brokers. If your investing life is “I have a general investment account next to my ISA, I reinvest dividends, and I want the dividend income totted up for my tax return,” Sharesight is a strong tool for the job. One gap UK investors should know about: as of October 2026, Sharesight does not offer a capital gains tax report for UK portfolios, so CGT is still a job for you or your accountant.
Where it falls short: it is an investments tracker, not a net worth tracker. Your house, your cash savings, your loans, your pension wrappers as a wrapper concept (rather than the holdings inside) — none of that is the product’s focus. The 10-holding cap on free is also tight; most real portfolios outgrow it on day one.
- Pricing: Free (10 holdings); paid £6 / £14 / £21 per month billed annually (UK, as of October 2026).
- Best for: UK, Australian, and New Zealand investors who want serious dividend and income reporting on their stock and ETF holdings.
- Skip if: You want a full net worth picture (assets and liabilities), or you don’t want to pay for multi-currency reporting that other tools include for free.
For the long version, see Sharesight vs TrackMyStack.
3. Parqet — The German Favourite, Now in English
Parqet is a German portfolio tracker with a polished, design-led product and more than 400,000 users. It has an English UI now, supports 40+ currencies, handles German broker quirks well, and has built deep auto-sync integrations with brokers German investors actually use, particularly Trade Republic — and its Autosync is available on the free plan.
The pitch is “your wealth always in sight” and it lives up to that visually — the dashboard is one of the better-designed in the category, with a dividend calendar and allocation views (the deeper analysis — X-Ray, dividend forecasts, the tax dashboard — is on Plus). Data storage is in Germany, the company is open about not making money from personal data, and the onboarding is fast (import a broker file or run Autosync, done).
The trade-offs: Parqet is investment-led — strong on stocks, ETFs, crypto, and dividends, lighter on the rest of the balance sheet. Savings, gold, or property go in as “additional assets,” and the free plan allows five of them. Autosync covers German brokers (Trade Republic, Scalable Capital, ING, comdirect, Consorsbank); outside Germany you are importing files. Pricing as of October 2026: a real free tier, Plus at €11.99/month (three months free if you pay annually), and Investor at €29.99/month.
- Pricing: Free tier; Plus €11.99/month; Investor €29.99/month (as of October 2026).
- Best for: German, Austrian, and Swiss investors who use a German broker (especially Trade Republic) and want their transactions imported automatically.
- Skip if: Your broker isn’t one of the Autosync ones, or most of your net worth isn’t in securities.
4. Portfolio Performance — Open Source, Desktop-First, ECB-Native
Portfolio Performance is the answer for European investors who looked at “subscription portfolio tracker” and instinctively reached for an open-source desktop app instead. It runs on Windows, macOS, and Linux, stores everything as XML in a file you control, calculates True-Time-Weighted and Internal Rate of Return properly, and uses the European Central Bank’s published exchange rates for foreign currency accounts.
The desktop app is free. The whole thing. It is open source under the Eclipse Public License. There’s also a companion mobile app for iOS and Android that reads the same data file, for viewing on the go; editing stays on the desktop, and custom mobile dashboards are an optional paid extra.
What you get: serious performance analytics, correct treatment of fees and taxes in your returns, historical price loading from a long list of sources (Yahoo Finance, AlphaVantage, CoinGecko, and others), CSV/JSON export, configurable rebalancing based on a target asset allocation. What you give up: it is a desktop application with a learning curve, and the phone app only shows what you have already set up there. You are doing this at a laptop, intentionally.
- Pricing: Free, open source (optional paid dashboards in the mobile app).
- Best for: Technical European investors who want maximum control, ECB-correct multi-currency, and zero subscription fees.
- Skip if: You want a mobile-first product, or “install a desktop app and import broker statements” sounds like a project you’ll abandon by week two.
5. Ghostfolio — Open Source With a Cloud Option
Ghostfolio is a Swiss open-source portfolio tracker with both a free self-hostable version and a managed cloud offering. The cloud Basic tier is free with unlimited transactions and accounts. Premium cloud is $48/year as of October 2026 (a one-time payment, no auto-renewal) and unlocks portfolio summary, allocations, performance benchmarks, and a built-in FIRE calculator. Self-hosting gets you those features for free.
It supports multiple currencies, multiple languages (English, German, French, Italian, Dutch, Spanish, Portuguese, Polish, Japanese, Chinese, and more), and is an independent, bootstrapped project that ships consistently. Self-hosting is a real option if you have a homelab and are comfortable with Docker.
Where it fits: somewhere between Portfolio Performance and Parqet — more modern and web-based than the former, more open and self-hostable than the latter. Lighter on auto-sync than Parqet, lighter on tax reporting than Sharesight.
- Pricing: Free Basic (cloud) or self-hosted; Premium $48/year for advanced features (as of October 2026).
- Best for: Open-source-friendly European investors who want a web app instead of a desktop app and may eventually self-host.
- Skip if: You want polished mobile apps with home-screen widgets, or you don’t care about the open-source angle and would rather have broader auto-sync.
6. getquin — The Social German Option, Now Bank-Linked
getquin launched in Germany in 2020 as a portfolio tracker with a noticeably more social slant than Parqet — it leans into community posts and discussion around your holdings — and now pitches itself as a whole-wealth platform. As of October 2026 the free plan includes unlimited bank and broker connections and a net worth overview; Premium (€89.99/year) adds AI-powered portfolio analysis and detailed allocation breakdowns, and Wealth (€149.99/year) adds financial planning, goals, and a retirement plan.
It’s worth a mention because some readers will be choosing between Parqet, getquin, and DIY. Functionally, getquin is fine for tracking; the community layer is either a useful nudge or noise depending on your taste. It does now cover more than investments — bank accounts through its connections, and property or collectibles added by hand. Connections are optional (you can import or enter trades manually), but the product is built around linking accounts, which is the opposite emphasis to a manual tracker.
- Pricing: Free; Premium €89.99/year; Wealth €149.99/year (as of October 2026).
- Best for: European investors who are happy to link their bank and broker accounts and like a community / discovery angle.
- Skip if: You want a private, no-signup tracker that never asks for bank access — the linked, community-first orientation is the opposite of that.
What’s the Best Net Worth Tracker for UK Investors Specifically?
Three honest picks, depending on what you actually want:
- For private, full net worth tracking in GBP, with no bank links: TrackMyStack. Set GBP as your home currency, hold your ISA / SIPP / GIA in their right currencies, add your house and your mortgage, and you’re done.
- For dividend and income reporting on a taxable UK account: Sharesight on a paid plan. Pricing runs from £6/mo to £21/mo billed annually as of October 2026, and the taxable income report is genuinely useful when the tax year ends. It won’t do your capital gains for you.
- For maximum control and zero subscriptions: Portfolio Performance, if you’ll commit to running a desktop app.
Empower, Monarch, and Mint-replacement budgeting apps don’t make the UK list because they don’t really work for UK accounts. Kubera works in the UK and is excellent if your situation justifies the price; for most UK investors it doesn’t.
What’s the Best Net Worth Tracker for European Investors Specifically?
- For private, multi-currency net worth tracking with a polished mobile app: TrackMyStack. Works the same way regardless of whether your home currency is EUR, CHF, SEK, NOK, DKK, PLN, or anything else.
- For German-broker auto-import: Parqet, especially if you’re a Trade Republic user.
- For a free, bank-linked net worth overview: getquin, if you’re comfortable linking accounts.
- For free, ECB-native, deep performance analytics: Portfolio Performance.
- For open-source with a cloud option: Ghostfolio.
The American net-worth-app conversation effectively passes Europe by — Empower won’t link your bank, Monarch isn’t available here, and Mint is dead. The European market has its own healthy answer set, and TrackMyStack fits the privacy-first slot in it cleanly.
What About Investors Outside Europe?
The same logic holds further afield, with one twist: in a few countries the local account-linking infrastructure is good enough that a domestic app is worth a look first.
- New Zealand and Australia: Sharesight is home turf. If you also want your bank accounts in the picture, PocketSmith (also built in New Zealand) offers local bank feeds and a net worth page. TrackMyStack prices ASX- and NZX-listed shares and ETFs, takes NZD or AUD as the home currency, and a KiwiSaver or super balance goes in as a manual holding.
- India: INDmoney syncs Indian stocks, mutual funds, EPF, and bank balances through depositories and account aggregators, and its net worth tracking is free. If all your money is in India, start there. Where it gets harder is money in two countries — a salary in AED or GBP and a flat in Pune — which is where a multi-currency tracker earns its keep. TrackMyStack prices NSE- and BSE-listed shares, with INR (or AED, or GBP) as the home currency.
- Japan: Money Forward ME is the big domestic name: it links Japanese banks, cards, and brokerages, and has a free plan. TrackMyStack prices Tokyo-listed shares, with JPY as a home currency, for anyone who would rather not hand over bank logins or who holds assets outside Japan.
- Malaysia, Kenya, and the Gulf: Here manual tracking is the realistic route for much of the balance sheet — EPF and ASB balances in Malaysia, SACCO deposits and money market funds in Kenya, end-of-service benefits in the Gulf. TrackMyStack prices Bursa Malaysia and Saudi Exchange shares; Nairobi- and UAE-listed shares aren’t in its catalog, so those go in as manual holdings you update yourself. MYR, KES, AED, SAR, and QAR all work as home currencies.
Frequently Asked Questions
What is the best net worth tracker for UK and European investors? TrackMyStack for most people. It is a private net worth and portfolio tracker that supports a separate currency per portfolio (GBP, EUR, CHF, etc.) with totals in your chosen home currency, requires no signup, and does not depend on US-centric bank aggregators. It is free, with an optional Premium subscription.
Why don’t apps like Empower, Monarch, and Mint work for UK or European investors? Empower needs a US phone number to sign up and only links US institutions. Monarch is available only in the US and Canada and doesn’t convert between currencies. Mint shut down in 2024. They are excellent products inside North America and largely unusable outside it.
Which net worth tracker handles multi-currency properly? TrackMyStack, Portfolio Performance, Ghostfolio, Parqet, Sharesight (with the multi-currency valuation report on its Standard and Premium plans), and Kubera all handle multiple currencies properly — meaning each holding is valued in its own currency and converted to your home currency at current rates, rather than being silently treated as USD. Avoid trackers where “multi-currency” means a single dropdown for the entire app, or no conversion at all.
Is there a free net worth tracker that works outside the US? Yes — TrackMyStack’s free tier (end-of-day prices, multi-currency portfolios, export, biometric lock) and Portfolio Performance (free, open source, desktop) are the strongest free options for non-US investors who don’t want to link accounts. Ghostfolio’s free Basic cloud tier is also a credible option, and getquin’s free plan works if you’re happy to link your bank.
Which tracker is best for UK ISA and SIPP investors? TrackMyStack if you want a single private app for ISA + SIPP + GIA + cash + property + mortgage, denominated in GBP. Sharesight if you also hold a taxable general investment account and want its dividend income reported for your tax return — inside an ISA or SIPP there is no tax to report, and Sharesight doesn’t track the wrapper or your wider net worth.
Which tracker is best for German Trade Republic users? Parqet: its Autosync imports your Trade Republic transactions, including dividends, and it’s available on the free plan. If you also want a private, whole-net-worth view that includes your real estate and your euro cash, pair it with TrackMyStack or use TrackMyStack alone with manual entry of your Trade Republic positions.
Do I have to link my bank account to track my net worth? No — and outside the US it’s often the wrong choice anyway, given patchy aggregator coverage and recurring Open Banking consent renewals. Manual-entry trackers (TrackMyStack, Portfolio Performance, the manual side of Kubera) work without any bank link. You enter what you hold; supported asset prices update automatically. More in the best net worth tracker without linking bank accounts.
The Bottom Line
If you live somewhere whose currency isn’t USD, the popular American net worth apps mostly aren’t for you — not because they’re bad, but because they were built for a different country’s banking infrastructure. The honest non-US shortlist is shorter than the search results suggest.
For private, multi-currency, full net worth tracking with no signup and no bank-link dependency, TrackMyStack is the best fit for the largest set of UK, European, and international investors. For dividend and income reporting on stocks specifically, Sharesight. For German broker auto-sync, Parqet. For free open-source desktop, Portfolio Performance. For an open-source web option, Ghostfolio. If all your money is in India or Japan, a domestic app (INDmoney, Money Forward ME) is worth a look. Kubera is the international high-end if your balance sheet justifies the price.
Pick the one that matches the question you actually want answered. If that question is “show me my whole net worth, in my actual currency, without me having to hand my bank credentials to anyone” — start with TrackMyStack.